

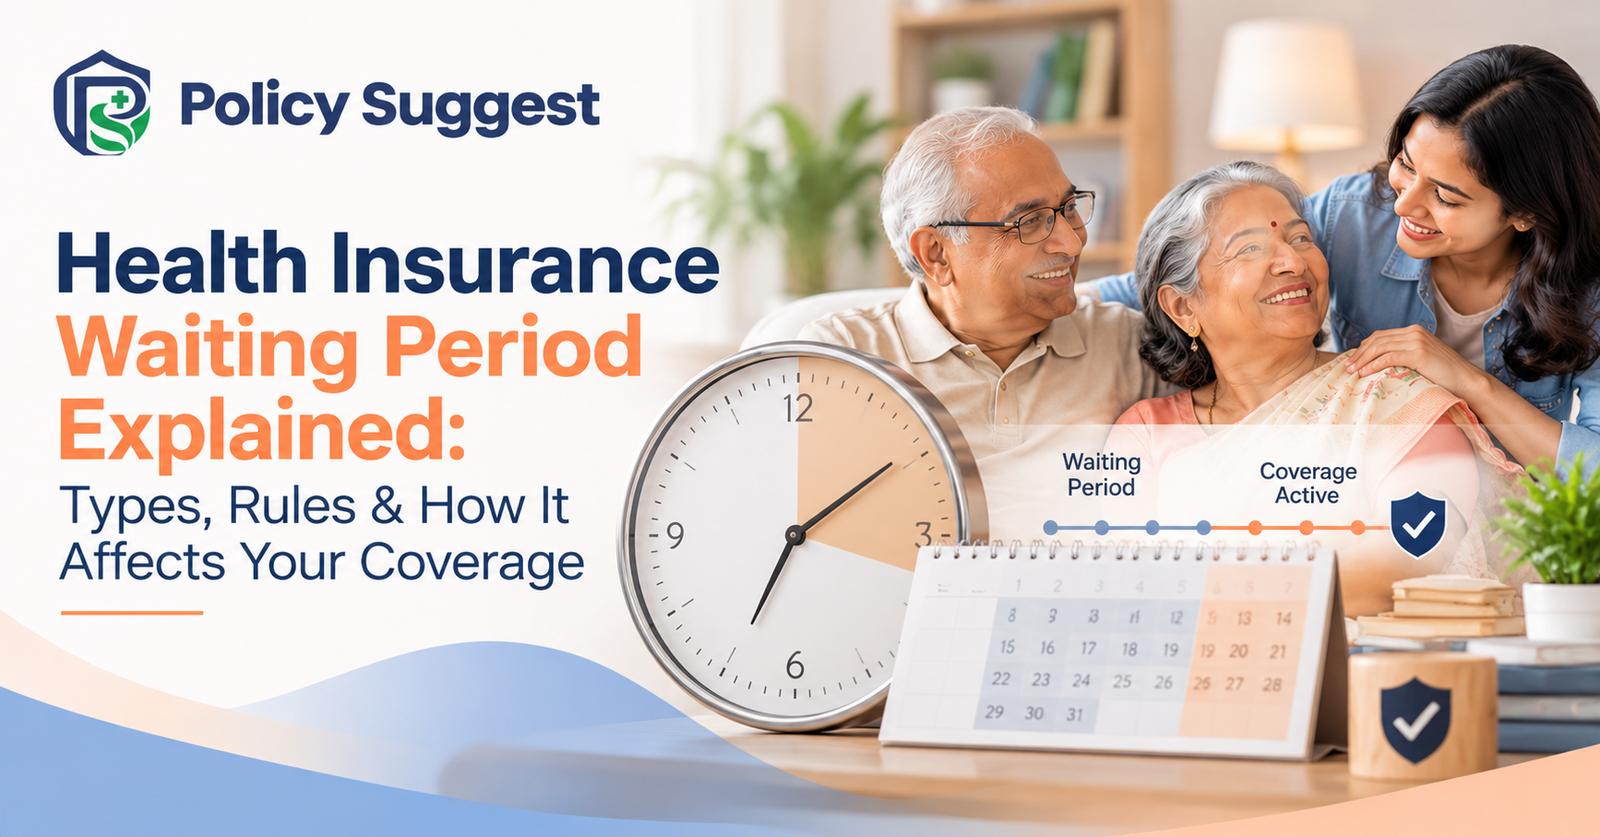
Buying a health insurance policy is not only about knowing the sum insured. You also need to understand when your coverage actually begins for different types of medical treatment. This is where the health insurance waiting period becomes important.
A waiting period is a specified time during which certain claims may not be payable under the policy. The exact duration and conditions depend on the insurer and product. Understanding these rules before buying health insurance can help you avoid surprises at the time of a claim.
What Is a Health Insurance Waiting Period?
A health insurance waiting period is the time you may need to complete before coverage becomes available for certain treatments, illnesses, or conditions under your policy.
This does not necessarily mean that your entire health insurance coverage is inactive. Different sections of a policy can have different waiting periods. For example, an initial waiting period may apply broadly, while a separate pre-existing disease waiting period may apply to medical conditions you already had when the policy began.
Because waiting periods vary by product, always check the policy wording rather than relying on a general number.
Why Do Health Insurance Policies Have Waiting Periods?
Waiting periods are used to define when certain medical expenses become eligible for coverage. Health insurance is designed to protect against covered future medical expenses, and policy terms may therefore specify waiting periods for conditions or treatments that need special treatment.
For a customer, the important point is practical: a treatment that looks covered in a policy brochure may still be subject to a waiting period.
Understanding the waiting period in advance helps you choose a policy based on your actual healthcare situation.
Types of Waiting Periods in Health Insurance
Initial Waiting Period
Many health insurance policies have an initial waiting period for illnesses. The plans shared with Policy Suggest commonly mention a 30-day initial waiting period, while accident-related hospitalization may be treated differently under product terms.
This means you should not assume that every illness-related claim is payable immediately after purchasing a new policy.
Pre-Existing Disease Waiting Period
A pre existing disease waiting period applies to medical conditions that existed before the policy started, as defined by the product.
This is especially important for customers with diabetes, hypertension, asthma, or other diagnosed conditions. The products shared with Policy Suggest include examples of 36-month and other PED waiting-period structures. Some products also provide optional ways to modify or waive a waiting period for specified conditions, subject to additional premium, underwriting, or acceptance of the benefit.
The key is to check exactly which condition is covered, from what date, and under what terms.
Specified Disease Waiting Period
Certain named illnesses or procedures may have a separate waiting period. The product material shared with Policy Suggest includes examples of a 24-month specified disease waiting period.
This can apply even when a medical condition was not pre-existing, depending on the policy's definitions and exclusions.
Treatment-Specific Waiting Periods
Some policies can also specify waiting periods for particular treatments, procedures, or categories of care. These must be checked in the product's policy wording.
Do not assume that a treatment is immediately covered simply because hospitalization is generally covered.
How Waiting Period Affects Your Health Insurance Coverage
Waiting periods influence when specific benefits become payable.
For example, suppose a new policy has an initial waiting period of 30 days and a three-year waiting period for pre-existing diseases. An illness arising after the policy starts may become eligible after the applicable initial period, while treatment related to a pre-existing condition may remain subject to its longer waiting period.
That distinction can be critical for families buying health insurance for parents or anyone with an existing medical history.
Waiting Period vs Exclusion
These terms are not the same.
A waiting period delays eligibility for a covered condition for a defined time.
An exclusion means the particular expense or condition is not covered under the relevant policy terms.
For example, if a condition has a 24-month waiting period, it may become covered after that period if other conditions are satisfied. If the condition is permanently excluded, completing 24 months does not automatically create coverage.
Read both sections carefully before you buy a health insurance policy.
Can Waiting Periods Be Reduced?
Some insurance products offer optional benefits or modifications that can reduce a waiting period for pre-existing diseases or specified conditions.
The plan references provided to Policy Suggest include products offering options such as modification of the PED waiting period and specific disease waiting period, while some offer defined Day 1 options for selected conditions subject to loading or acceptance.
These are product-specific benefits. A customer should not assume that every insurer offers them or that every pre-existing condition qualifies.
Waiting Period and Portability
When moving from one health insurance policy to another, waiting-period credits can depend on portability rules and the applicable policy terms. The exact treatment should be confirmed with the insurer and policy documents before switching.
This is one reason it is important to maintain continuity and understand the terms before allowing an existing policy to lapse.
How to Compare Waiting Periods Before Buying
Start by identifying medical conditions and treatments that are relevant to you and your family.
Then check the initial waiting period, pre-existing disease waiting period, specified disease waiting period, and any treatment-specific conditions.
Next, look for available waiting-period modification options. Check whether they are included in the base plan or available only as an optional benefit for additional premium.
Also check whether any special benefit has additional conditions. Terms such as Day 1 coverage can apply only to defined diseases or after the insurer accepts the applicable option.
Finally, read the exclusions and definitions. Waiting periods make sense only when read together with the rest of the policy wording.
Why Waiting Period Matters for Health Insurance Buyers
Waiting periods are particularly important when you are purchasing insurance for older parents, someone with a pre-existing disease, or a family member who is likely to need treatment soon.
Buying early can give you more time to complete applicable waiting periods before a medical need arises. It also gives you an opportunity to compare plans while focusing on long-term coverage rather than trying to solve an immediate problem with a policy that may have conditions you did not expect.
How Policy Suggest Can Help
Health insurance waiting periods can be confusing because the rules differ from one plan to another. Policy Suggest helps customers explore health insurance options from leading insurers and understand the differences in waiting periods, benefits, limits, co-payment, deductibles, and other important conditions.
Instead of focusing only on the headline premium, we help you ask the questions that matter before choosing a health insurance policy.
Final Thoughts
A waiting period is an important part of health insurance coverage. Knowing the initial, pre-existing disease, specified disease, and other applicable waiting periods can help you understand when different benefits may become available.
The right plan is not simply the one with the shortest waiting period. It is the one whose coverage structure, conditions, and benefits fit your healthcare needs.
Take time to read the policy terms, disclose medical information accurately, and compare relevant options before purchasing. Policy Suggest can help make that comparison easier to understand.
FAQs
1. What is the health insurance waiting period?
It is a defined period during which certain treatments, illnesses, or conditions may not yet be eligible for coverage under the policy.
2. What is a pre existing disease waiting period?
It is the period that may apply before treatment related to a condition that existed before policy inception becomes payable, subject to the policy definition and terms.
3. Is the initial waiting period applicable to accidents?
Product terms can treat accident claims differently. The policy wording should be checked for the exact rule.
4. Can a health insurance waiting period be reduced?
Some products offer optional waiting-period modifications or defined benefits for selected conditions, subject to their terms, underwriting, and additional premium where applicable.
5. Does every health insurance policy have the same waiting period?
No. Waiting periods can differ by insurer, product, illness, treatment, and optional benefits.
6. Can Policy Suggest help me understand waiting periods?
Yes. Policy Suggest can help you explore relevant plans and understand the waiting periods and other conditions before you choose.